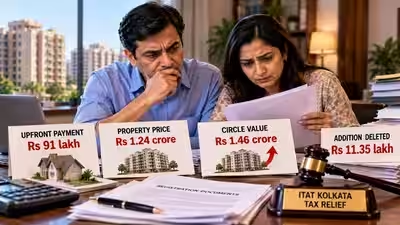
Homebuyer paid Rs 91 lakh upfront for a Rs 1.24 crore property, but circle value rose to Rs 1.46 crore by registration; why ITAT Kolkata gave her tax relief and deleted Rs 11.35 lakh addition

You agree to purchase a property and even give a portion of the payment. But by the time the property registration happens, the circle rate in the area has gone up, increasing the stamp duty, which leads to you getting a tax notice. What do you do then?In one such case, the Kolkata bench of the Income Tax Appellate Tribunal (ITAT) has ruled on this. Let’s find out what the case was about, and why ITAT gave tax relief to the homebuyer.
What the case is about
In 2021, the taxpayer and her husband entered into a registered agreement to purchase an immovable property for a total price of Rs 1.23 crore.However, the registered conveyance deed was subsequently executed in 2023 without any change to the original purchase price of Rs 1.23 crore.However, by the time the property was registered in September 2023, its stamp duty or circle value had climbed to around Rs 1.462 crore.The transaction was picked for scrutiny.“The agreed price was consistent with the circle rate applicable at the time. Further, the buyers had paid a sizeable advance of Rs 91 lakh through banking channels on or before the agreement date,” CA Suresh Surana tells ET.Surana explains that the Assessing Officer (AO) compared this revised stamp duty valuation with the actual consideration of Rs 1.23 crore and considered the resulting difference a benefit received by the homebuyers.Under Section 56(2)(x), there is applicable taxation of such a difference in the buyer’s hands if the stamp duty value of the property is higher than the purchase consideration by more than the greater of Rs 50,000 or 10% of the consideration.Here, the difference of approximately Rs 22.71 lakh exceeded 10% of the agreed purchase price of Rs 1.23 crore.As the taxpayer owned half of the property, the AO added around Rs 11.35 lakh to her taxable income under the head “Income from Other Sources”, hence invoking Section 56(2)(x).The addition of this Rs 11.35 lakh was equivalent to the woman’s 50% share of the gap between the property’s stamp duty value of Rs 1.462 crore and the agreed purchase consideration of Rs 1.235 crore.
Why did ITAT Kolkata rule in favour of the homebuyer?
The taxpayer contested the assessment before the CIT(A), arguing that the Assessing Officer had relied on an incorrect date for determining the property’s value.She maintained that the sale price had been established under a registered agreement in January 2021 itself. A significant part of the consideration had also been paid through banking channels by that stage, Surana explains.The CIT(A), however, rejected her plea and sustained the addition through an order dated March 31, 2026. The taxpayer then took the matter to the Kolkata ITAT.In her appeal before the Tribunal, she invoked the specific relief available under the provisos to Section 56(2)(x).Surana says these provisions address transactions in which the date of the agreement determining the consideration differs from the date of registration. In such cases, the stamp duty value applicable on the agreement date can be taken into account rather than the higher value prevailing when the property is eventually registered.To qualify for this relief, the buyer must have paid at least a portion of the consideration through the prescribed banking or electronic payment methods on or before the date of the agreement.The Tribunal considered both the registered purchase agreement and the conveyance deed executed later.“The taxpayer had entered into a registered agreement on January 22, 2021, the consideration of Rs 1.235 crore reflected the circle value prevailing at that time, and Rs 91 lakh had already been paid through banking channels,” says Surana.He adds that the conveyance deed’s execution in September 2023 was not a valid reason to replace the circle rate applicable when the parties had originally agreed on the purchase price with the subsequently increased valuation.Surana explains that Section 56(2)(x) contains a safeguard specifically intended to deal with such circumstances. Circle rates and property valuations can rise during the period between the execution of a binding purchase agreement and the eventual registration. If the buyer is able to demonstrate that a genuine agreement was entered into earlier and that payment was made through the prescribed banking channels, the law allows the stamp duty value as on the agreement date to be considered.The AO had instead applied the higher stamp duty valuation in force on September 18, 2023. Finding this approach incorrect, the ITAT removed the Rs 11.35 lakh addition, overturned the CIT(A)’s order and allowed the taxpayer’s appeal.